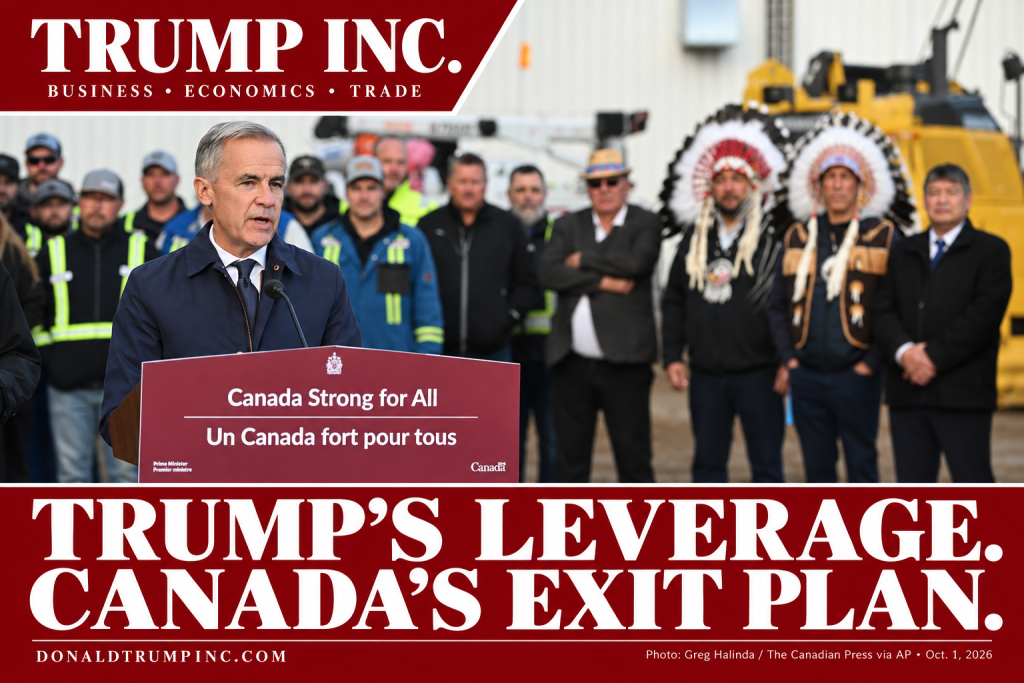
TRUMP’S LEVERAGE. CANADA’S EXIT PLAN.
DT Inc. Analysis | Energy, trade and the price of having another customer.
Cover photograph: Mark Carney announcing Pacific Link in Fort McMurray, Alberta, October 1, 2026. Greg Halinda / The Canadian Press via AP. Source photograph and reporting. Trump Inc. branding and headline added with AI assistance.
A supplier with another customer negotiates differently.
Canada’s proposed Pacific Link oil pipeline puts that business principle at the center of its relationship with the United States. The question for Donald Trump is whether today’s bargaining pressure encourages Canada to build the infrastructure that makes tomorrow’s pressure less effective.
Canada wants an alternative. Turning that ambition into profitable oil shipments is the expensive part.
What Canada actually announced
On October 1, Prime Minister Mark Carney announced Pacific Link’s designation as a project of national interest. Ottawa intends to consolidate federal review and finalize project conditions by September 1, 2027.
The proposal would add capacity to move approximately one million barrels of crude oil daily from Alberta to the Pacific coast for overseas sale. The federal order and explanatory note describe a route from Bruderheim, Alberta, to a deepwater port near Delta, British Columbia, with an estimated cost of C$35.2 billion to C$43.7 billion, including contingency.
This is a major regulatory commitment. Full construction financing is still being developed, and final design and commercial agreements remain unfinished. September 2027 is the target for project conditions, rather than the date oil starts flowing.
The negotiating asset: somewhere else to sell
The Canada Energy Regulator reports that 90.1% of Canada’s crude exports went to the United States in 2025. That concentration gives Canadian sellers a powerful reason to seek additional outlets.
DT Inc.’s interpretation: a credible route to Asian customers could improve producers’ position when negotiating with American buyers. The option to redirect future supply can matter even when the supplier continues selling substantial volumes to its existing customer.
Think of a business whose largest customer knows it has few practical alternatives. A second viable sales channel changes the conversation. The first customer remains valuable, but its terms must compete with another offer.
You can control the negotiation today—and give the other side a reason to build an exit tomorrow.
That is the tension in Trump’s use of trade leverage. Pressure can secure concessions. It can also make the cost of reducing dependence look more attractive. Pacific Link is a plan to create that option; its announcement alone does not eliminate American bargaining power.
Who pays for the exit plan?
The federal explanatory note sets out Pembina’s planned 10% economic interest through construction, with an opportunity for another 10% after commercial operation. Trans Mountain Corporation and Alberta Petroleum Marketing Commission would share the remaining interest equally. At least 10% would be offered for purchase to Indigenous peoples.
The proposed structure places most initial ownership with public entities. That gives taxpayers an interest in the project’s returns and exposes them to its financial risks. The precise allocation of financing, guarantees and overruns needs to be judged from the completed agreements.
Canadian producers could benefit from more sales options. Pipeline owners need enough paid throughput to cover capital and operating costs. Those are different tests: a strategically useful project can still produce disappointing investment returns.
America has a dependency too
The same regulator reports that Canada supplied 63.4% of U.S. crude oil imports in 2025. The relationship carries economic value on both sides of the border.
If additional overseas demand improves Canadian sellers’ terms, some American buyers could face stronger competition for supply. The outcome would depend on production growth, shipping costs, crude quality, refinery requirements and prices elsewhere. A new pipeline’s capacity does not mean an equal quantity will automatically disappear from U.S. deliveries.
Canada could expand output, shift destinations, or do both. Treating the proposal as an immediate American fuel shortage would outrun the evidence.
The contracts will tell the story
Watch for binding shipping commitments, credible financing and final project conditions. Then examine whether overseas prices, after pipeline tolls and ocean freight, justify the investment.
Long-term commitments matter because they turn an ambition to diversify into revenue that can support construction. Cost overruns and delays matter because they increase the price of that independence. Indigenous participation, environmental safeguards and marine facilities also affect whether the project can deliver.
Trump Inc.’s earlier question was “Don’t buy the building—control the lease.” Canada’s pipeline poses the next question: what happens when the other party decides to build another doorway?
DT Inc. take: Trump’s leverage is strongest when Canada’s alternatives are limited. Pacific Link could change that equation—if Canada can finance it, build it and sell enough oil through it to make the exit plan pay.
Sources and disclosure: Reporting based on the Prime Minister of Canada’s October 1 announcement, the federal order and explanatory note, and Canada Energy Regulator trade data. Economic scenarios and judgments are DT Inc. analysis. AI-assisted article.